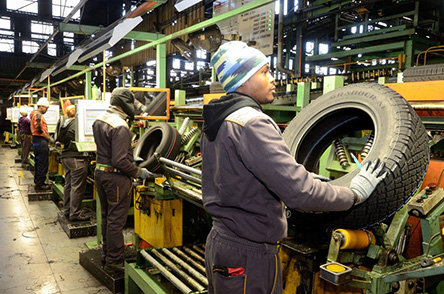
The 43-year-old tyre manufacturing firm, General Tyre East Africa (GTEA) will soon be revived following the Tanzania government decision to place it under the state-owned National Development Corporation, which will team up with the National Social Security Fund in the process. According to Zitto Kabwe, the chairman of the Parastatal Organisations Accounts Committee, the government stands to lose $20 million if the company is declared bankrupt and will have to pay $28 million to acquire shares of Continental AG. “It is a wise decision for the government to revive since it means job retention and creation and will also be a source of revenue for the government,” said Kabwe, adding that: “It is vital for the government to revive other companies which are under-performing and those that are about to be declared bankrupt for the sake of the country’s economic future.” Kabwe also noted that Tanzania needs to have its own manufacturing industries to stimulate the economy and provide for the needs and wants of the local and international market as well. In the early 1970s to the late 1980s, GTEA was one of the largest tyre maker in East Africa with a production capacity of about 1,000 tyres a day, supplying to the eastern and central African market. The company was established in 1969 under a partnership between the Tanzania government and General Tyre USA before it sold its shares to Continental AG of German. Continental AG acquired 38 per cent stake in the company in the mid 1990s leaving the government with a majority shareholding at 62 per cent. Information shows that productivity at the factory started to decline at the end of the 1990s when imported and second-hand tyres flooded the domestic market. In the year 2005, the firm acquired a loan of about $10 million from NSSF under the guarantee of the government to revitalise the factory but it failed to do so. The debt is said to have appreciated to $14 million due to accumulated interests. GTEA stopped production in 2007 when Continental AG demanded yet another $2 million loan from the government, which turned down the request. Minister for Industry and Trade, Cyril Chami says that Continental AG has apparently refused to discuss with the government on the way forward. “The government cannot therefore let the property remain idle. We have to bring the plant back to operation,” he said. “NSSF will acquire shares in GTEA as part of compensation for $10 million loan it advanced to the company in 2005,” said Dr Chami. TANZANIA'S TYRE MARKET Tanzania is in talks with six multinational companies over plans for a joint venture to revive General Tyre East Africa, the giant tyre manufacturing plant in Arusha. The state-run National Development Corporation (NDC) said that three Asian corporations and another three from America, Europe and Africa have approached the government, seeking a partnership to revive General Tyre, which used to supply tyres throughout East and Central Africa. “We are finalising our due diligence and talks to end a troubled partnership with Continental AG of Germany in a bid to transfer the General Tyre assets to NDC. After that, we will negotiate with prospective companies,” SAID NDC’s acting director of heavy industry Ramson Mwilangali. Continental AG, with 26 per cent shares, has since 2006 been embroiled in a dispute with the government over a poor supply chain and low production levels, which resulted in the closure of the company in 2009, locking out about 400 workers. In July 2008, the firm petitioned the Tanzania government, which owns 74 per cent of General Tyre, for a renewal of the contract. But reports said it failed to outline a concrete business plan on how to make General Tyre profitable. Continental AG was asked to explain how General Tyre’s debts amounting to $20 million by December 2008 would be settled. But Continental AG demanded to be paid an outstanding debt of $3.321 million. Records show that before its closure in 2009, the factory’s capacity was 320,000 tyres per annum. The firm is expected to employ nearly 400 workers and produce 1,000 quality, heavy-duty tyres a day. This means that, without interruptions, the plant could produce 250,000 tyres a year, earning the country $63 million if an average price per tyre is $250. General Tyre will first supply tyres for all government vehicles before it markets to the private sector in the country and in East Africa. Tanzania, East Africa’s second largest economy, has seen vehicle imports increase by nearly 70 per cent in a single year. Official government data, which does not include government, police, army and donor-funded vehicles, shows that 67 per cent of registered vehicles were light passenger vehicles with a carrying capacity of less than 12 passengers. The revival of General Tyre offers a much-needed alternative not only for the country, but also for East Africa in general, which imports the bulk of its tyres from China, Japan, India and Dubai. Many African countries prefer importing low-priced Chinese tyres rather than the expensive European and American brands. Gasper Mpehongwa, a lecturer at Tumaini University, said the revival of General Tyre will create competition for Sameer Africa Ltd — the only East African tyre manufacturer — leading to better quality at lower prices. Former General Tyre sales manager Phillip Mweta said the EAC tyre market is huge and even having two local manufacturers will not satisfy it. The state is preparing to pump in over $20 million to breathe life into the defunct General Tyre East Africa, whose production lines stalled in 2009 due to, among other factors, importation of cheap tyres. Chinese tyres The revival of General Tyre offers a quick fix, not only for the country, but also for East Africa in general, which imports the bulk of its tyres from China, Japan, India and Dubai. The cheap imports have been blamed for the increase in road accidents. In Tanzania, traffic police reports show that road accidents claimed the lives of 3,582 people last year. During the same period, over 1,000 bus passengers accounting for 18 per cent of the total deaths also perished. Police reports blame most of these road accidents on tyre bursts. Chinese tyres are gaining popularity in several African markets. Many African countries are price-sensitive markets and prefer to import low-priced Chinese tyres rather than the expensive European and American brands. As a result, China has emerged as a leading exporter of tyres to African countries like Tanzania. Analysts say most illegally imported tyres have a quality problem emanating from storage; some are poorly stored in hot godowns for months, which seriously compromises quality.
Tyre Market in East Africa
folder_open East Africa , Market Reports
When it comes to tyres, the African continent is one of the fastest growing markets for the global tyre industry. The rapid growth of the middle class in many African countries has pushed demand for automobiles to an all-time high – in turn creating a growing market for all kinds of tyres: passenger car tyres, off-the-road tyres, industrial tyres, agricultural tyres, truck, bus and trailer tyres as well as motorcycle and bicycle tyres. The rising demand for tyres in Africa has led to stiff competition between tyre manufacturers from all across the world seeking to garner a major share of the market for tyres in the new and emerging African markets. Traditionally, European tyre manufactaures had had a monopoly over the African markets and many European brands were top selling tyres in many African countries. However, in recent times, European tyre firms are beginning to loose ground to Chinese and other Asian brands in many emerging markets not only in Africa, but around the world. Chinese tyres are gaining popularity in several African markets. Many developing countries, specialy in Africa, are price-sensitive markets and prefer to import low-priced Chinese tyres rather than the expensive European and American brands. As a result, China has emerged as a leading exporter of tyres to many African countries in recent times. Players in the tyre business worldwide are not renowned for fair trade practices and Kenya is no exception. Some years back, all tyre companies operating in the United States were summoned by the Federal Bureau of Investigation (FBI) after accusations that the multi-million dollar firms were engaged in cartel-like cost-fixing in the country. In Kenya, a significant bulk of uncustomed products have entered the local market. Firestone, which also imports tyres from the parent company, Bridgestone Corporation of Japan, say they have been in touch with the treasury over the issue, but the practice continues. Tyres attract a duty of 35 per cent which, according to business analysts, should place the prices of imported and locally manufactured tyres roughly at par, with only marginal price variations on some brands. But international tyre manufacturers say retail and wholesale prices of some foreign products in the market are well below the expected minimum if costs of production, transport, insurance and duty are considered, an indication that there is illegal dumping. Apart from lack of infrastructure, most illegally imported tyres, have a quality problem emanating from storage; some are poorly stored in godowns in hot places like Dubai for months, which seriously compromises quality. Before Firestone established its manufacturing plant in Kenya nearly two decades ago, all tyres were imported. The government, eager to promote import-substitution, imposed quotas and tariffs to protect the local industry, which gave the company a virtual monopoly. However, some imports were allowed since there were vehicles in the market which could not use the company's products. Fifteen percent of Firestone, a member of the Sameer Group of Companies, is controlled by Bridgestone Firestone Inc of the US, which, in turn, is a subsidiary of Japan's Bridgestone Corporation. Japanese company bought Firestone Tyre and Rubber Corporation of the US, which also owns much of war-ravaged Liberia's rubber plantations. Before 2005, buoyed by a weak Japanese yen, Bridgestone was the world's foremost tyre producer. But as the value of the yen against major hard currencies shot up, and dollar-based sales plummeted, it was overtaken by Michellin. In recent times, the tyre companies in Kenya have carried their rivalry to the airwaves, each claiming superior products. While Pirelli and Michellin needed introduction since they were new in the market, a Firestone survey showed that the Michellin campaign was having a significant impact on sales and Firestone was forced to embark on their own campaign. Michellin is exclusively marketed by Kingsway Tyres who, however, declined to comment. Pirelli, which is sold locally by Nyanza Petroleum Company, has confined its marketing strategy to advertisements painted on Stage Coach buses, which, ironically, use Michellin tyres! Although the most popular Michellin adverts target matatu and small cars, Firestone claims there has been no major impact by their rivals in this area. Then there is the issue of warranty. While Firestone products boast that they "come with a written guarantee", Michellin advertisements proclaim "the name is the guarantee". But Firestone is not daunted, offering replacement for any tyre damaged due to errors arising from manufacturing, stressing the fact that its tyres are tailor-made for Kenyan roads. Besides new tyres, there are also low-quality second-hand ones which soon wear out on the country's rough roads. The managing director of Pirelli (Europe), Valter Donati, says that most used tyres are dumped into the African market after exceeding the legal use limit in European and other developed countries. The thread of the tyres is so shallow that it makes nonsense of the cheap prices, and they also have a poor surface grip. An increase in tyre import duties has been requested for South Africa, owing to the large quantity of substandard tyres that are being brought into the country from China. The cheaper tyres provide unfair competition for local tyre manufacturers, who are concerned with the risk the thinner tyres pose to the safety of heavy vehicles such as taxis. The National Union of Metalworkers (Numsa) has asked Government to increase tyre import duties to stop the influx of cheap tyres. Supporting Numsa?'s campaign, South Africa'?s top four tyre manufacturers (Bridgestone, Continental, Dunlop and Goodyear) have brought the Government'?s attention to their safety concerns for the widespread use of tyres of inferior quality. The new Toyota Quantum taxis, a larger version of the minibus taxi, are most at risk of accidents caused by the cheap tyre imports. To cut costs, taxi drivers replace their 15-inch Quantum tyres with cheap 14-inch tyres, which are thinner and cannot carry the car's weight. The tyre manufacturers and NUMSA say that there is a marked increase in the dumping of Chinese tyres. "From 2000 to 2010, the imports of passenger vehicle tyres increased by 100 percent from one million to two million per year, while the imports of commercial tyres grew from 200 000 to just less than 840 000," says Etienne Human, the chief executive and president of the SA Tyre Manufacturing Conference (SAMTC). The effect is being felt by local manufacturers who are experiencing a significant decrease in demand as a result of the effects of the recession in the car industry. Bridgestone, Continental, Dunlop and Goodyear are currently cutting back on up to a quarter of their labour force. China?'s tyre production far outweighs the country's local demand for tyres, and so tyre dumping on foreign soil has become a necessary evil. Etienne Human said that the South African tyre manufacturing industry is losing more than Rands 1 billion per year as a result of the dramatic increase in tyre imports. He attributes this increase to sloppy checking systems by customs officials. As a result, imported tyres account for almost half of the tyres in the South African market. He also added that tyre manufacturers applied for anti-dumping import duties against Chinese companies but their application was unsuccessful. Despite the manufacturer?s? assessment that the tyres are of inferior quality, Sharma Iqbal, a deputy director-general at the Department of Trade and Industry said that all tyre imports were standardised and approved by the SA Bureau of Standards. So despite the best efforts of the most developed country in the African continent, the onslaught of the Chinese manufacturers continues. Chinese tyre manufacturers have, in a way, broken the myth about European technological superiority by producing high quality tyres at fraction of the cost. The European brands, used to charging high prices for their products, have finally been challenged and are now being forced to roll back their profit margins and compete with Chinese manufacturers. RECENT DEVELOPMENTS In a significant all-cash overseas deal worth about US$80 million, the board of directors of Apollo Tyres Ltd (ATL) approved the acquisition of the Durban-headquartered Dunlop Tyres International (Pty) Ltd (Dunlop South Africa). The 100 per cent equity buyout transaction, subject to regulatory approvals in both countries, would enable the US$ 726 million ATL to secure a toehold in the fast growing Africa region and also a strong presence in the South African tyre market. Besides the benefit of superior radial tyre technology, the acquisition would also enable the domestic tyre major to access the European market through the distribution network owned by the $200-million Dunlop South Africa. By virtue of the equity buyout of Dunlop South Africa, ATL would get to control Dunlop Africa Marketing UK (registered in the UK), which is a 100 per cent subsidiary of Dunlop South Africa and also the holding company of Dunlop Zimbabwe (which owns the Zimbabwe facility). Dunlop South Africa had 3,000 employees, two plants in South Africa (each 75 tonnes per day) and one plant in Zimbabwe (35 tonnes per day bias tyre facility of Dunlop Zimbabwe). At present, ATL's capacity in India is about 750 tonnes per day! Sarkar said that ATL has no plans of making any changes to the management of Dunlop South Africa. Moreover, the existing brands of the acquired company would be continued. Prior to this transaction, financial investors (comprising mainly private equity, individual investors and some holding by members of senior management) owned Dunlop South Africa. Sarkar expressed confidence that all regulatory approvals would be received easily. "As far as India is concerned, we have to only get a post-facto approval from the Reserve Bank of India as the transaction is lower than $500 million. As regards the South African Competition Commission, we don't foresee any problem," he said. Apart from Dunlop South Africa, the other three significant players in the South African market are Continental, Bridgestone and Goodyear. All the four players enjoyed nearly equal market share.
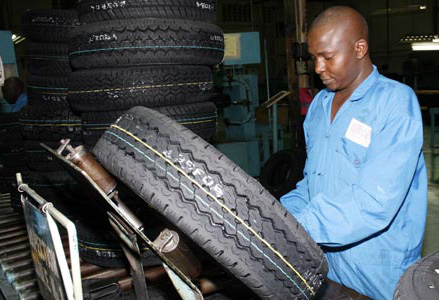
Sameer Africa to close its tyre manufacturing plant in Nairobi
folder_open East Africa , Market Reports
Sameer Africa, a leading tyre manufacturer in East Africa is planning to stop manufacturing of tyres at its Nairobi plant and shift the production offshore, possibly to India or China. The makers of popular Yana tyres, could earn higher margins through contracting-manufacturing, possibly with an Indian firm that has unsuccessfully bid to acquire Sameer in the past. The firm has been making losses for the last two years. Its best performance in the last five years was in 2013. However, the firm plans to retain its major brands even after handing over manufacturing to third parties. Sameer Africa has been fighting for survival from fierce competition from cheaper brands. Already, the firm has been selling Summit Tyre, a much cheaper imported brand in a bid to protect its fast-shrinking market share. By outsourcing production, Sameer Africa aims to lower production costs linked to friendlier taxation and cheaper energy prices in India and China. In essence,Sameer Africa will stop being a manufacturer and become a reseller and landlord. The firm would also plans to build a mall and several warehouses on a 100-acre parcel of land around its Mombasa Road plant-cum-head offices.
Ethiopia's Automotive Industry
folder_open East Africa , Market Reports
Ethiopia is among Africa’s most impressive growth performers over the past decade averaging 10.9% annual growth between 2005 and 2022. With a GDP of US$112 billion in 2022 it is the ninth largest economy in Africa and the third largest in Eastern Africa. After Nigeria, the country is also home to the continent’s second largest population of 120 million people in 2022 and a forecasted 150 million in 2025. Undoubtedly, Ethiopia is a relatively untapped investment opportunity in Eastern Africa especially in the manufacturing sector. Ethiopia’s automotive market is dominated by second-hand imported vehicles – particularly commercial vehicles. Commercial vehicles were Ethiopia’s second most valuable import overall in 2022, worth US$875 million. On the other hand, commercial vehicles were also Ethiopia’s highest earning automotive export in 2022. This can largely be attributed to Bishoftu Automotive Industry (BAI), an automotive manufacturing and assembly company run by the Ethiopian military. BAI specialises in assembling, upgrading, overhauling and localising buses, pick-ups, SUVs, trucks and military equipment such as tanks and armoured personnel carriers (APCs). Military vehicles are largely for the use of the Ethiopian military and African Union peacekeeping missions while civilian vehicles are supplied to local customers such as state-owned transport providers. Small quantities of commercial vehicles have been exported to neighbouring Somaliland. Increasing Numbers Ethiopia has the lowest motorisation rate globally, with only two cars per 1,000 inhabitants in 2015. Recent reports estimate that in 2022 there were 210,000 vehicles in use in Ethiopia, of which 125,000 were passenger vehicles and 85,000 were commercial vehicles. Between 2005 and 2022, total vehicles in use grew at a CAGR of almost 2.4%. According to Ethiopia’s Ministry of Transport approximately 84% of the market is passenger vehicles while commercial vehicles make up 16%. Second-hand vehicles in Ethiopia tend to appreciate in value due to high import duties and limited supply of vehicles. As a result, second-hand vehicles dominate the market. Approximately 85% of vehicles are second-hand imports, of which almost 90% are Toyotas.These vehicles are imported primarily from the Gulf States, through the Port of Djibouti. Automotive Sales Although there is almost no publicly available reliable data on vehicle sales in Ethiopia. It is however estimated that 18,000 vehicles are brought into Ethiopia each year. The majority of these are second-hand vehicles. Each year, 2,000 new Toyotas and between 5,000 and 7,000 used Toyotas are imported. Clearly, Toyota controls approximately 65% of the total market (new and second-hand) due to its reputation as being reliable and inexpensive to maintain. The main drivers of new commercial vehicle sales are construction, agri-business and retail while passenger vehicle sales are driven by government (including diplomatic corps) purchases. Vehicle affordability is further locked up by prohibitively high vehicle taxes of sometimes more than 220% depending on engine size. As taxes in Ethiopia are cumulative, excise tax is calculated on the customs duty, surtax is charged on top of the excise tax, and customs duty and final VAT is calculated once the surtax, excise tax and customs duty have been added. Imported vehicles may cost as much as three times the retail price of the vehicle outside of the country. Commercial vehicles, such as pick-ups, vans and trucks, have a lower tax rate than vehicles for personal use. Relative disincentives exist vis-à-vis personal vehicles compared to commercial vehicles. Diplomats and foreign investors are allowed to import vehicles duty-free. The supply-depressing character of foreign exchange shortages contributes to imbalances in the market and drives up the market price of vehicles, thus also having a negative impact on the affordability of vehicles in the Ethiopian market. Production and Assembly The Ethiopian Investment Commission (EIC) reports that 31 foreign vehicle investment projects (largely Chinese projects but also someinvolvement of European companies) and 73 domestic vehicle assembly investment projects have been licensed since 1998. This means that a total of 104 companies have been licensed for vehicle assembly in the country over the past two decades. However, only a few of these are operational, with the vast majority licensed at the pre-implementation stage. During the past decade, a number of leading international automotive companies have carried out market scoping exercises to assess the viability of Ethiopia as an assembly hub. However, due to the limited market size, large-scale investments by these automotive firms have not yet materialised. Although a number of assemblers source some components such as tyres locally, Ethiopia has no defined local content requirement. A number of assemblers indicated that they are instructed that local content should be approximately 30% in order to qualify for the 30% tax incentive associated with all local manufacturing, but that no written agreement exists between assemblers and the state. Due to Ethiopia’s tax system, which subjects vehicles to tax depending on their engine size rather than age or origin, it is often cheaper to import a second-hand vehicle with a smaller engine size than it is to assemble a vehicle locally, despite import taxes on these vehicles. Despite being home to the continent’s second largest population, the overall automotive market size remains small in the short to medium term for current and prospective assemblers and producers. However, Ethiopia’s strong government support for industrialisation and the development of auxiliary industries coupled with a large cost competitive labour pool, and sizeable investments in infrastructure (both physical and economic) could position the country favourably for automotive manufacturing in the long term to service both the regional and domestic market with price competitive vehicles. To achieve this, clear definitions of local content need to be developed. The country’s high tax rates on vehicles reduce the affordability of vehicles, especially given the low income of the population, and restrains the vehicle retail market. To address this, industry stakeholders should support the establishment of vehicle financing solutions, in order to encourage wider vehicle ownership. Taxes should be revised to also take the age of vehicles into account in order to provide incentives for locally produced vehicles.
Africa's Automotive Market
folder_open Market Reports
Africa’s automotive market is relatively small. In 2014, there were just over 42.5 million registered vehicles in use in Africa – a continent of approximately one billion people. As a result, the motorisation rate on the continent is only 44 vehicles per 1,000 inhabitants. This is far below the global average of 180 vehicles per 1,000 inhabitants, and lower than other developing regions such as Latin America (176) and Developing Asia, Oceania and the Middle East. In 2015, approximately 1.55 million new vehicles were sold or registered across Africa. South Africa, Egypt, Algeria and Morocco – all countries with established and rapidly developing automotive industries – together accounted for more than 80% of total new vehicle sales in 2015. Based on recent sales trends, some sources estimate that Africa’s passenger vehicle sales could reach up to 10 million units per annum within the next 15 years. Between 2015 and 2020, registrations and sales of new vehicles (passenger and commercial combined) increased by a compound annual growth rate CAGR of 3.6% on the continent. While coming from a low base and although slightly higher than the global average of 3.5%, total sales growth in Africa was significantly slower than other emerging regions such as Asia and the Middle East (8.9%), and Latin America (4.2%). Both the lower motorisation rate to date and new vehicle sales and registrations reflect the still relatively low purchasing power of African consumers relative to their emerging market peers. More importantly, the sizeable latent potential of the continent’s automotive market in the long term. Due to limited disposable income and the high cost of new vehicles, second-hand vehicles dominate the continent’s automotive retail sector. These are mainly imported. Based on in-market research, it is estimated that in the three major African countries like Ethiopia, Kenya, Nigeria at least 8 out of 10 imported vehicles are used vehicles. This is a common trend across the region given that Africa imports four times more automotive products than it exports, with automotive imports worth US$52 billion in 2020 and exports worth only US$13 billion in 2020. Key sources of used vehicles are the United States (US), Europe and Japan. The Middle East serves as a notable transit route for vehicles into East Africa. Imports of vehicles grew rapidly from 2003 onwards, coinciding with GDP per capita growth and a growing middle class on the continent. This was supported by high commodity prices at the time. South Africa dominates automotive trade on the continent, accounting for three-quarters of Africa’s automotive exports and 15% of imports in 2020. Automotive Market in Africa Africa’s market is the most underdeveloped automobile market in the world. Apart from South Africa, Morocco, Egypt and Algeria, the automotive market in rest of the countries is considerably small in comparison. The major reasons for this limited growth are the low-average income and the lack of a sizeable middle-class population. Also, the high lending rates have made ownership of a car restricted only to the wealthy and prosperous. Ghana, a promising market, has a car loan interest rate that fluctuates around 32%. Even in Nigeria, one of the biggest economies of the continent has a loan interest rate of about 12%. This makes taking a car loan an expensive proposition, which is hindering the automotive market in the country. Currently the new automotive industry in Africa is plagued buy the import of used cars from other countries. For instance, in Japan, where strict vehicle inspections force cars out of circulation after just a few years, vehicles are exported to countries like Kenya. To curb these practices and revive the local industry, the government plans to wind down imports of cars that are more than three years old by 2021. The market is segmented by the type of vehicles and geography. Passenger vehicles are expected to hold a greater market share, but commercial vehicles are expected to grow at a faster rate. THE WAY FORWARD Undoubtedly, Africa’s automotive sector is the final frontier for automotive growth. The viability of automotive assembly or production in Africa is regarded as limited in the short term, but has largely untapped potential in the long term. To date, new vehicle sales on the continent as well as the local production and assembly of vehicles have been limited by various factors such as a small market size, lower purchasing power, a less competitive operating environment and an insufficient policy environment. This has undermined the industry’s ability to reap economies of scale and thus supply price competitive vehicles to domestic and regional markets. To help unlock the markets of the countries evaluated, formalising and consolidating the automotive retail sector will be a priority in the short term. This will assist players across the automotive value chain to be closer to the consumer, at the same time educating the consumer about the benefits of new or certified pre-owned vehicles. It will also enable industry players to build local expertise and scalable capacity. As economies of scale at an individual country level will be challenging to achieve in the short term, domestically created capacity could be further scaled. This should be achieved through an export-orientated focus of both building regional value chains around components and plugging the continent into the global automotive supply chain through cost-competitive production in the medium to long term. This global value chain is already undergoing a shift, with two external mega trends underway that will help to unlock Africa’s automotive potential. Firstly, the strong growth of vehicle sales in emerging markets generally reflects the global shift of sales from developed, high-wage countries to emerging, low-wage countries. This shift of sales has been accompanied by the shift of production capacity to these growth markets, in order to respond to increasing pressure on margins. The relocation to low-wage emerging markets allowed automotive manufacturers to save on labour costs and to be closer to the end consumer. In order to reduce logistics costs and to ensure uninterrupted supply with parts and components, tier-1 suppliers are increasingly relocating to the vicinity of the automotive plants they supply. While in 2002, seven out of 10 vehicles sold were in high-wage countries. Many expect this to reverse by 2023. Africa Automotive Directory The African Automotive Directory compiled by Africa Business Pages has emerged as a helpful resource for those looking for buyers of automotive spare parts in Africa. The Africa Automotive Directory lists all major auto parts importers in 49 African countries and is available for immediate download in Excel format. This special directory is updated every six months is available for sale at the Africa Business Pages B2B portal at a nominal cost of US$350. The Africa Automotive Directory has helped many exporters, manufacturers and dealers of automotive spare parts connect with their business counterparts in the African markets and develop direct business relations and expand their sales and distribution network in key African markets.
Kenya's Automotive Market
folder_open East Africa , Market Reports
Kenya’s GDP per capita is expected to reach US$1,432 by the end of 2015 and to grow at a CAGR of 7.5% between till 2020. This is expected to result in an increase in private consumption and amongst other things, drive the sales of motor vehicles. Expenditure on the purchase of cars, motorcycles and other vehicles accounted for 1.5% of total consumer expenditure in 2015 and is expected to remain relatively stable to 2025 as incomes rise. The volume of imported cars and motorcycles has been on the increase due to the availability of attractive credit from financial institutions and the rise of the middle class. According to the Kenya National Bureau of Statistics (KNBS) the volume of imported vehicles between 2003 and 2012 have grown at over 300% from 33,000 units to 110,474 units. Passenger vehicles were Kenya’s fourth largest import overall in 2015, valued at approximately US$440 million and making up 2.4% of total imports (by value) while commercial vehicles ranked seventh, valued at US$380 million. If the current trend of 10% to 12% growth per annum on vehicle imports is to be maintained, Kenya will have five million vehicles on the road by the year 2030. In the early 1980s, Kenya banned the importation of FBUs. At the time, Kenya was assembling approximately 18,000 units locally. Following a World Bank-imposed structural adjustment programme (SAP) in mid-1993, the country removed a large number of trade restrictions and the economy underwent liberalisation, allowing the importation of FBUs. As no age limit was imposed on vehicles imported, second-hand imports, some up to 20 years old, flooded the market. To date, Kenya is still highly dependent on imports to meet domestic demand, with imports making up 94% of bilateral automotive trade and second-hand vehicles accounting for over 80% of those imports. Both passenger and commercial vehicles feature in Kenya’s top ten imports by value. As the regional gateway on account of the Port of Mombasa, 99.9% of Kenya’s automotive exports are to other African countries, with Uganda and Tanzania being the biggest markets. Africa Automotive Directory The African Automotive Directory compiled by Africa Business Pages has emerged as a helpful resource for those looking for buyers of automotive spare parts in Africa. The Africa Automotive Directory lists all major auto parts importers in 49 African countries and is available for immediate download in Excel format. This special directory is updated every six months is available for sale at the Africa Business Pages B2B portal at a nominal cost of US$350. The Africa Automotive Directory has helped many exporters, manufacturers and dealers of automotive spare parts connect with their business counterparts in the African markets and develop direct business relations and expand their sales and distribution network in key African markets. Kenya: Booming Market for Automotive Spare Parts Although Kenya used to have large volumes of grey and illegal imports, this has been reduced through a number of government interventions, and as a result the used imported market is now more regulated. The Kenya Revenue Authority and the Kenya Bureau of Standards are situated at entry ports such as the Port of Mombasa and Jomo Kenyatta International Airport to monitor and record the arrival of vehicles. Vehicles entering through these ports that are destined for countries other than Kenya, such as Uganda, have to receive their clearance and payment confirmation of registration fees from the destination country before they are able to leave the port of entry. Vehicles Numbers It is estimated that approximately 80% of Kenya’s total vehicle fleet are second-hand vehicles, with a total vehicle fleet of around 1.4 million units in 2015. In 2014, the average age of vehicles on Kenya’s roads was 15 years, which has resulted in high levels of pollution, frequent break-downs of vehicles, and a large non-genuine spare parts industry developing. The total number of vehicles in use grew at a CAGR of 7.7% between 2005 and 2015. Figures for Kenya’s motorisation rate differ depending on the source, and range between 26 and 28 vehicles per 1,000 persons. This is forecast to increase to 31.5 in 2019, reflecting vehicle ownership growing faster than Kenya’s population. Vehicle Sales According to the KNBS, a total of 112,536 vehicles were registered in 2015 – this included newly registered and re-registered vehicles. KNBS does not differentiate between the registration of new vehicles and the re-registration of used vehicles, whereas the Kenya Motor Industry (KMI) only records new vehicles sold. KMI states that 19,523 new vehicles were sold in Kenya in 2015, reflecting the dominance of used vehicles in the retail market. In 2015 light and heavy commercial vehicles combined accounted for 86% of total vehicle sales, highlighting the importance of larger vehicles, such as light commercial vehicles, minibuses, heavy trucks, and buses. Sedans and SUVs made up 14%. Heavy commercial vehicles too saw the highest growth, with a CAGR of 17.5% between 2005 and 2015 and thus were key drivers underpinning new vehicle sales growth over that period. Sales of new vehicles in Kenya are driven by the demand for transportation in the construction, mining, agri-business, tourism, energy and retail sectors. The government and in particular its law enforcement and security authorities are significant buyers of new vehicles. The most popular second-hand vehicles cost between Ksh350,000 and Ksh500,000. In light of current growth drivers, business fleet purchases make up a significant proportion of total vehicle sales. It is expected that firms investing in Kenya’s economy will drive stronger demand for business fleet purchases, particularly given the number of major infrastructure investments in the country in recent years, notably the Lamu Port-South Sudan-Ethiopia-Transport (LAPSSET) Corridor Project. The Kenya Local Government Sector Reform Strategy has given greater budgetary autonomy to local governments (Counties), resulting in County governments expanding their vehicle fleets and further driving local demand. Production and Assembly Kenya’s automotive market is largely focused on retail and distribution of vehicles, and after-sales support in servicing and spare parts sales. Small scale assembly of motor vehicles is done at three assembly plants, the General Motors East Africa (GMEA) plant in Nairobi, the Associated Vehicle Assemblers (AVA) plant in Mombasa and the Kenya Vehicle Manufacturers (KVM) plant in Thika. All three of the plants are operating below their capacity. However, the country’s good infrastructure, relative to other countries in the region, as well as its physical and strong economic position within the East Africa Community (EAC), make it a potential hub for automotive assembly and production in the region. Recently, counties have been lobbying with investors to set up manufacturing hubs in their regions to provide employment and promote trade within their jurisdictions. In February 2016, Machakos County signed a deal with Ashok Leyland to set up an assembly plant in the county recently. Locally produced vehicles are assembled from CKD kits with minimal locally produced inputs. KMI defines CKDs as a package of most or all of the individual parts of a vehicle, as separate pieces. All of the pieces are brand new from their country of origin. As Kenya does not locally assemble sedans (except occasionally on an ad hoc basis), commercial vehicles dominate Kenya’s domestic production – a similar focus employed in the early stages of Thailand’s automotive sector. In 2015, Kenya assembled 9,295 vehicles, of which 921 (close to 10% of assembly) were light commercial vehicles (LCVs) such as pick-up trucks, and the rest of the 9,295 were heavy commercial vehicles (HCVs) such as trucks and buses. The assembly of motor vehicles in Kenya grew by almost 32% from 2013 to 2015. High growth of 54.4%, 43.7% and 20.8% was registered in the production of pick-ups, trucks and buses respectively. Kenya’s vehicle assembly figures are forecasted to almost double between 2013 and 2019. Policy Environment The Kenyan government has identified the automotive and auto parts industry as a major economic driver in the Kenya National Industrialisation Policy Framework released in 2010. In order to build up its automotive industry, the framework identified five policy statements: 1. The development of a 40 hectare automotive industrial park in Machakos by 2012; 2. Providing incentives to encourage locally assembled vehicles and the production of autos parts in order to gradually replace imported second-hand vehicles with locally assembled vehicles; 3. The establishment of a National Automotive Industry committee which would be tasked with developing the automotive value chain and co-ordinating the industry; 4. Impose high tariffs on automotive parts that could rather be produced locally to encourage the growth of a local industry; and 5. Set up a joint venture with an established automotive manufacturer by 2016 with the goal of domesticating the company within ten years. While to date, most of the goals are yet to be realised, the government has devised a number of policies such as a 30% local input requirement for locally assembled vehicles (although this had not been implemented at the time of writing). The Kenyan government has also committed to supporting entrepreneurs in the automotive components industry, developing the auto components supply chain, placing high tariffs on imported automotive components that could be manufactured locally and the formation of a national automotive industry board. All vehicles imported for use in Kenya attract an IDF (Import Declaration Fee of 2.25% of CIF) and RDL (Railway Development Levy of 1.5% of CIF) tax and are depreciated based on the year of manufacture and registration. Vehicles imported as CKDs attract 0% import duty but can only be imported by a licensed manufacturer. CKD kits are assembled in a KRA Bonded Warehouse facility and are only then required to pay IDF fees. However, as soon as these are removed from the bonded facility and are used in Kenya, they are subject to value added tax (VAT), excise duty and the RDL. Vehicles assembled in Kenya for export are not subject to domestic taxes. In July 2015 the Ministry of Industrialisation proposed policy measures in the Policy Framework for Motor Vehicle Assembly in Kenya to complement the National Industrialisation Policy Framework. The policy aims to promote new investments in the country’s automotive industry and for Kenya to become a globally competitive vehicle manufacturer. The 2015 framework aims to impose a tax of 2% on all imported FBU units, the creation of an Automotive Innovation Fund (AIF) to support research and development in the sector and the inclusion of the sector in special economic zones (SEZs), with the SEZ Bill passed at the end of 2015. Local assemblers and eventually producers located in SEZs will be afforded benefits including ten year tax holidays, low utility rates, and export credits. The new framework, similar to the National Industrialisation Policy Framework, aims to create a National Automotive Council (NAC) which will be equipped to address aspects relating to the assembly and manufacture of vehicles, including capacity building and the proposal and implementation of incentives. The 2015 Policy Framework for Motor Vehicle Assembly in Kenya differs from the 2010 National Industrialisation Policy Framework in that engagement with the private sector has been more consistent. Rather than focusing on industrialisation as a whole and manufacturing more broadly, the new framework is centred on the automotive industry with a structure to drive local production. Stakeholders in Kenya’s automotive industry were engaged with to a greater degree than before and as a result the 2015 framework is seen as an improvement on the previous framework and a step in the right direction. In contrast to other EAC markets, vehicles older than eight years are not permitted for import into Kenya. Although, there is anecdotal evidence of cases of importers forging import documentation of older vehicles, this law is largely abided by and the industry believes that government implements it effectively. All imported vehicles undergo a roadworthiness inspection and the Ministry of Industrialisation is in the process of lowering the legal age limit of second-hand vehicles imported into the country to five years. This should reduce the number of imported used vehicles, as newer second-hand cars will be more expensive. Within the EAC, products substantially transformed (i.e. from CKD to full assembly) in any of the member states (Burundi, Kenya, Rwanda, Tanzania and Uganda) should be sold on a duty-free basis in the other member states. In 2009 EAC member states ratified a Common External Tariff (CET) of 25% on vehicles imported into the region, hoping to drive local assembly. However, the other EAC countries have requested that the implementation of the CET be put on hold and continue to impose duties on vehicles assembled in Kenya, which currently is the only country in the EAC with the capacity to assemble vehicles. Tanzania and Uganda’s arguement is that vehicles assembled in Kenya do not abide by Tanzania and Uganda’s local content requirement of 35% and therefore do not qualify for duty-free access to these markets. Vehicles assembled in Kenya are therefore imported into these markets with a CET of 25%. This has resulted in imported vehicles having an advantage over vehicles assembled regionally, as cars arriving from Japan in Uganda and Tanzania are cheaper than vehicles assembled in Kenya. However, the Kenyan government is engaged in talks with other EAC states and it is likely that the issue will be resolved in the short term. Beyond the domestic policy focus on the automotive sector, Kenya was also identified by the EAC as a potential vehicle production hub for the region in its draft East African Industrialisation Strategy 2010-2030 released in 2010. The draft argued for encouraging major carmakers that already imported vehicles into the region to rather produce locally. However, this was left out of the final EAC Industrialisation Strategy 2012-2032, where the assembly of cars, buses and tractors and vehicle spares was identified as having the least growth potential in the region of 20 industries considered. Industry stakeholders interviewed however recognised the opportunity of both the regional parts value chain as well as the EAC as an export market for Kenyan produced vehicles and parts. One of the greatest inhibitors to the advancement of Kenya’s automotive sector is the proliferation of second-hand vehicles available in the market. Decreasing the age of cars allowed for import while simultaneously decreasing the affordability of these cars by increasing the taxes levied on them should drive sales of more affordable, newer, roadworthy, and locally-assembled cars. Incentives to assemble locally, such as tax breaks or waiving of import duties for parts, will make it more affordable to assemble vehicles in Kenya in the short to medium term and could encourage production in the long term. Also, definitions of local content need to be developed and aligned to the other EAC members’ automotive and manufacturing policies. These need to be accepted regionally, especially within the EAC, for Kenya to pursue an East African automotive manufacturing hub and export strategy. The development and promotion of auxiliary industries in partnership with the vehicle assemblers will enable automotive companies to source high-quality inputs locally, further strengthening the case for local assembly. The Kenyan government is particularly aware of the need to improve the country’s infrastructure, with programmes in place to increase electricity accessibility and either refurbish or build new transport infrastructure. Despite new investments in the country, Kenya’s automotive sector is relatively stagnant and runs the risk of being side-lined in the long term by other regional players such as Ethiopia, which has a more progressive approach to industrialisation.
Nigeria's Automotive Market
folder_open Market Reports , West Africa
With a population of close to 180 million and a GDP of US$493 billion in 2015, Nigeria is the most populous country with the largest economy in Africa. Despite the current economic challenges facing the country due to low oil prices and a weakened currency, Nigeria still reveals robust economic growth of 2-4% in the medium term. Owing to the lack of domestic vehicle production, Nigeria is highly dependent on imports to meet its domestic demand. In 2014, passenger vehicles constituted the second-largest import category after petroleum oils or bituminous minerals. Overall automotive related imports stood at US$6.9 billion (passenger vehicle imports: US$2.9 billion) accounting for approximately 11.5% of Nigeria’s total imports. While auto imports recorded rapid growth between 2004 and 2014, the current slowdown in the economy and the recent introduction of high import duties on vehicles linked to the new automotive policy has led to approximately a two-third contraction in vehicle imports according to industry players. Second-hand vehicles dominate the import market. It is estimated that approximately 10% of vehicles imported to Nigeria are brand new. A large share of second-hand vehicles are imported from the US, given that vehicle specifications in this market are more in line with the demand and taste of Nigerian consumers, which is not always met by entry-level models from Europe. Before the hike of import duties on second-hand vehicles, Nigeria imported more than 100,000 cars per year from the the US. In 2015, imports from the US had plummeted to less than 40,000 units. In addition to direct shipments to Nigeria, the Port of Cotonou in neighbouring Benin is a key transit point for second-hand vehicles destined for the Nigerian market. It is estimated that 85% of Benin’s used vehicle imports end up in Nigeria. In 2013, the European Union (EU) and the US exported approximately 300,000 cars to Benin. Based on the import figures for Benin, an additional 255,000 used cars from the EU and the US entered Nigeria via Benin. There is no culture of maintenance in Nigeria – people drive their cars until they break down and then fix them. Vehicle Numbers Depending on the source of data, the current vehicle fleet in the country ranges from 1.3 million vehicles to 10 million vehicles. According to the Federal Road Safety Corps the total fleet size was 1.65 million units in 2015, of which approximately one third are concentrated in Lagos State. Even applying the least conservative estimate of vehicles in use, namely 10 million vehicles, Nigeria’s motorisation rate is approximately one-third that of the global motorisation rate with less than 60 vehicles per 1 000 people. Due to the New Automotive Industry Development Plan (NAIDP) launched in 2014 that increased the prices for imported vehicles, and the economic slowdown triggered by low oil prices, Nigeria’s growth in fleet size slowed down remarkably in 2015. However, it is expected that in the short term fleet growth will stabilise in a range between 4.5% and 5.5% per annum. Vehicle Sales Despite being the most populous country in Africa, Nigeria’s new vehicle sales lag behind less populated countries such as Algeria, Egypt, Morocco and South Africa. According to industry players, the overall new and second-hand market combined ranges between 500,000 and 1 million units per year. Smuggling, grey imports of second-hand vehicles and the lack of reliable data however, make the exact size of Nigeria’s vehicle market and fleet size difficult to quantify. Challenges concerning the licencing and identification of vehicles further contribute to this difficulty. Imported second-hand vehicles, so-called tokunbos, dominate the Nigerian vehicle market as only a small segment of society is able to afford new vehicles. A representative of a leading automotive firm estimates that a mere 2% of the population is able to afford new vehicles given the current economic and financing environment. While commercial banks offer vehicle finance, accessing these credit facilities has become increasingly unattractive to individual consumers as credit facilities are provided at interest rates above 20% per annum and require at least a 10% down-payment. Commercial banks usually require repayment of vehicle loans within four years, due to the rapid depreciation of the value of vehicles given poor road conditions. According to one of the most established vehicle finance providers, the monthly repayment amount should not exceed 35% of the monthly income of the borrower. The short repayment-period as well as the high interest rates present a key challenge for low- and middle-income households when it comes to accessing vehicle finance. Due to the limited accessibility to and expensive financing of vehicles, new vehicles remain out of reach for most Nigerians and the largest share of current vehicle demand comes from the business community. Corporate buyers account for approximately 70% of overall new vehicle purchases, indicating the suppressed demand from private buyers, arguably the market segment with the largest growth potential. Through recently introduced promotional offers by banks in partnership with selected vehicle dealers, customers are able to access finance at a discounted rate for a limited number of vehicles and models. Indeed, the provision of alternative financing products, especially in-house financing by the automotive companies, is seen by industry players as a key requirement for the growth of the local market. However, in the absence of affordable finance solutions, secondhand vehicles remain the more attractive option for private vehicle buyers. According to a representative of a leading automotive company, second-hand passenger vehicles accounted for 80% of sales in 2014. The share of tokunbos in the commercial vehicle market is even larger, reaching up to 90% of the market according to a leading commercial vehicle manufacturer. New vehicle sales are dominated by Toyota which accounts for almost one third of new sales. Hyundai and Kia have established themselves as increasingly serious competitors to Toyota due to their competitive pricing and improved image in terms of quality. In 2015, the three Asian brands accounted for half of new vehicle sales in the country. The economic slowdown, the depreciation of the naira and the increase in vehicle prices due to the import duty hike had a substantial impact on new vehicles sales in 2015. Although vehicle sales saw positive growth post the global financial crisis, total new vehicle sales dropped by more than half in 2015, compared to 2014. The sharp decline of sales highlights the absence of sizeable and competitive domestic assembly that could provide an affordable alternative to imports and the dependency on vehicle imports to meet domestic demand. Production and Assembly Nigeria is no stranger to automotive assembly and manufacturing. Already in the 1970s Nigeria started assembling motor vehicles. In the 1970s and 1980s, the federal government of Nigeria partnered with six international automotive and commercial vehicle manufacturers to produce passenger and commercial vehicles locally from CKD kits. According to the National Automotive Council (NAC) these six companies had an initial installed capacity of 149,000 units per annum during the 1970s and 1980s. “Sometimes, cars are imported to be stripped for parts as availability of genuine parts is limited.” In addition to these plants, the Federal Government entered into five more agreements with international automotive companies to establish assembly plants in 1982, according to the National Automotive Design and Development Council Nigeria. These agreements included the establishment of plants by Isuzu in Maiduguri, Mazda in Umuahia, Mitsubishi in Ilorin, Nissan in Minna and Peugeot in Gusau. However, these plans did not materialise. Furthermore, due to inconsistent policy implementation, corruption, declining patronage by local and federal government departments and lack of reliable power supply, the output and capacity utilisation of the six existing plants declined rapidly. Symptomatic of the demise of Nigeria’s automotive industry was the stop of production activities by Peugeot Automobile Nigeria (PAN), Nigeria’s largest manufacturer, in 2010. Since then assembly plants have been lying dormant. By 2012, all of the country’s automotive manufacturers had been privatised as the government exited the existing partnerships, eroding any incentives for government departments to purchase locally assembled vehicles The launch of Nigeria’s NAIDP in 2014 and the subsequent hike in import tariffs for vehicles has attracted the interest of leading international carmakers and has led to the resumption of small scale vehicle assembly in the country. While the high import tariffs are aimed at encouraging local assembly, the sharp drop in vehicle sales in Nigeria in 2015 is a strong indication that this measure had an adverse impact on overall vehicle prices in the absence of a sufficient assembly base that could provide substitutes for imported vehicles. In 2015, local assembly was only able to cover 10-15% of the new vehicle market. According to a senior representative of one of the automotive companies present in Nigeria, approximately 1,000 passenger vehicles were assembled in Nigeria in 2015 – an even more conservative estimate. Currently, 35 companies are licensed to produce by the Nigerian Automotive Council under the NAIDP. Despite the increased focus on the automotive industry, the sector’s contribution to Nigeria’s GDP remains low at 0.07%. At present the vehicles are assembled from imported SKD kits with a limited degree of local inputs-sourcing due to the lack of a reliable and adequate domestic supplier base. While current assembly figures are low, with Peugeot Automobile Nigeria recording the largest number of vehicles assembled in 2015 with 400 units, the automotive companies aim at increasing their annual output in order to capitalise on the long-term growth prospects of the Nigerian market. However, due to the current economic slowdown, expansion plans are likely to be delayed as reflected in the decline of employment levels in some of the assembly facilities. Africa Automotive Directory The African Automotive Directory compiled by Africa Business Pages has emerged as a helpful resource for those looking for buyers of automotive spare parts in Africa. The Africa Automotive Directory lists all major auto parts importers in 49 African countries and is available for immediate download in Excel format. This special directory is updated every six months is available for sale at the Africa Business Pages B2B portal at a nominal cost of US$350. The Africa Automotive Directory has helped many exporters, manufacturers and dealers of automotive spare parts connect with their business counterparts in the African markets and develop direct business relations and expand their sales and distribution network in key African markets.
Nigeria's Tyre Market
folder_open Market Reports , West Africa
Globally, the leading tyre manufacturers today include Bridgestone, Michelin, Goodyear, Continental, Pirelli and Sumitomo (for Dunlop brand). World production of tyre is estimated to be 860 million units annually. Within Africa, significant tyre factories exist in Egypt, South Africa and Zimbabwe. Nigeria tyre market is now emerging as a leading importer of tyres in West Africa. The Nigerian tyre industry took off shortly after independence in 1960 with both Dunlop Nigeria Plc and Michelin Nigeria Limited establishing their respective manufacturing outfits. By the Year 2005, the combined annual local capacity was 2.25m units, representing 75% of Nigerian tyre market at that time. These two companies were the only tyre manufacturing outfits in Nigeria, and indeed the West Africa region. Africa accounts for less than 1% of the global tyre production, while Nigeria then produced only about 0.2% when its factories were fully operational before the owners of the two tyre factories (Dunlop Nigeria Plc and Michelin Nigeria Ltd) shut them at the end of 2008 and 2006 respectively, due to the harsh operating environment (infrastructural deficiency, tariff structure, etc). THE NIGERIAN TYRE MARKET In the last forty years and starting during the oil boom years, the increased number of cars in Nigeria over saturated Nigerian roads. The demand for tyres kept growing over the years and the tyre market, like many other markets in the country at that time, was a seller’s market. This growth continued until the economy started to decline in the last twenty years as a result of the world’s energy crisis, coupled with our own internal problems. Over the last 20 years or so, it had become difficult to buy new cars and most people had to resort to second hand (Tokunbo) cars. The market reacted by importing an increasing number of second hand cars into the country from different parts of the world, which became more affordable and influenced the car tyre market in several ways. In the Nigeria tyre market, there are both premium and budget (cheaper tyres), but the ever declining purchasing power of the consumers continued to make the budget tyres more attractive. Budget tyres (which account for about 80% of the Nigerian total tyre market) are imported mainly from Asian countries. These are usually low quality, low priced tyres, allowed into the country so long as they meet the standards set by Government agencies. Standards Organisation of Nigeria is expected to inspect these tyres on arrival. The global tyre market is estimated to be $190 billion while the tyre market in Nigeria is about $1.0 billion. The total Nigerian tyre market size is estimated to be 5.7 million units (car, van & light truck – 3.9m and truck – 1.8m) with a projected growth rate of 3-5% annually). There are about 150 brands of tyres in the Nigerian market with five dominant players namely: Dunlop, Michelin, Bridgestone, Pirelli and Firestone. By 2008, all the imported brands accounted for about 90% share of the market as against only 25% in 2005. Today, all the tyres in the Nigerian market are imported following the cessation of local tyre manufacturing. DOWNLFALL OF THE TYRE INDUSTRY IN NIGERIA Dunlop was incorporated on October 21, 1961, beginning with tyre imports and started production in 1963. The raw materials for tyre manufacturing are natural and synthetic rubber, carbon black, wires, zinc oxide and other chemicals. All the raw materials are imported except zinc oxide, mineral oil and natural rubber. Warri Petrochemicals produced 2 out of 6 grades of carbon black used by the tyre industry locally. Dunlop Nigeria Plc, when the import duty tariff on both car & truck was 40%, started importing Heavy Truck Radial (HTR) in 2000. The company subsequently embarked on the local production of Heavy Truck Radial, which was part funded by National Automotive Council (NAC) through its NAC- Automotive Development Fund. The HTR factory was commissioned by in 2005. Barely 4 four months after, there was a reduction in HTR tariff to 10% from 40%. In December 2006, Michelin Nigeria Limited shut its factory due to the harsh operating environment (infrastructural deficiency, tariff structure, etc), disposed its equipment and left, after 43 years of operations in Nigeria. Dunlop Nigeria Plc continued despite the fact that the problems that made Michelin to relocate out of Nigeria also affected it but remained with the hope that those problems would be addressed. Unfortunately, these problems made it difficult for Dunlop to dispose its tyres (both truck and car) at reasonable margins because it had to compete with imports at 10% duty rate and the attendant infrastructural disadvantage which increased its production cost by about 40%. Both companies (Dunlop and Michelin), before and after 2006, had on several occasions drawn the attention of the government at all levels to these problems. Regrettably, not much response was received from the relevant authorities, and because it could not continue to erode its shareholders funds, Michelin was forced to stop production at its factory by December 2006 while Dunlop followed the same path in December, 2008. They have both since joined the league of those importing tyres into Nigeria. The closure of the two tyre factories in the country have resulted in loss of over 3,000 direct and several thousands of indirect jobs, closure of many smaller feeder cottage industries that serviced the factories, non payment of taxes etc. REVIVING THE TYRE INDUSTRY IN NIGERIA The Nigeria tyre market is generally placed under “strategic industrial sector “in any nation. In Nigeria, during the Civil war 1967-1970, because of the location of Michelin factory in Port Harcourt, it could not function, and as a result virtually all the tyre requirements of the Nigerian Armed forces were supplied completely and exclusively by Dunlop Nigeria Plc. Most of the tyres used by the peace keeping forces in Africa were equally supplied by Dunlop Nigeria. The mass transportation sector in Nigeria is currently facing major challenges. The rail and water mode of transportation are not fully developed and this leaves road mode of movement as the most viable, significantly strategic and most preferred, and by extension, tyre becomes the singular most important component in the road mode of transportation. The national tyre demand annually is very large, enough to accommodate at least five different tyre factories with capacity of 20 million kg or 1m car/van tyres each. Thus, the combined capacity of over 100m kg will just be about enough to optimise the market in Nigeria. This excludes the rest of West Africa which is about another 50% of Nigeria tyre market. These tyre factories have potential of creating over 10,000 direct jobs, and several thousands of indirect job openings. Creation of smaller feeder cottage industries, payment of taxes, better security situation and positive impact on the national economy are all the positive implications of a functional Nigeria tyre market. The natural rubber, carbon black and other petro chemicals available in Nigeria will also be value addition processes. The subsidiary Company of Dunlop, Pamol Nig. Ltd., has 15,000 hectares of land across Cross River, Delta and Edo states and employs not less than 10,000 persons directly and indirectly in its rubber plantation business. Michelin, on the other hand, has bigger rubber plantations in Ogun and Edo states but while Dunlop used its raw rubber in the local production of tyres up to December 2008, Michelin exported its raw rubber out of the Country and then imports their finished tyres back in to the country, since January, 2007. Considering the strategic need for the tyre industry and its attendant benefits, it is imperative to revive the industry without further delay. The new auto policy introduced by the government recently is a positive step in this direction. To make the implementation of the policy more effective, there is need for a monitoring body consisting of SON, Customs and tyre manufacturers’ representatives to regulate tyre importation into the country. The ongoing reforms and efforts in the power sector are commendable and should continue. This will address quite a number of manufacturing challenges facing the tyre industry in the country. DEMAND IN NIGERIA TYRE MARKET The Nigeria tyre market is very strategic for the nation and should be revived. The import-friendly policies that are crafted ostensibly out of not envisaging the full implications on the Nigerian economy should be discouraged. The recent auto policy announced by the Nigerian government is a positive step in this direction. The current situation where tyres that can be manufactured locally are imported will only help to fuel job creation in other countries while unemployment in Nigeria country continues to rise, with all the security implications. The Nigeria tyre market can play a crucial role in job creation too. Recent policy articulations and implementations by our government in respect of power, cement, rice, sugar, etc gives a lot of room for optimism that the new National Automotive Policy would also be faithfully implemented. Specifically, the policy as it affects encouraging local tyre manufacture includes pioneer status which gives 7-year tax holiday, zero duty on imported tyre manufacturing equipment, 5% import duty on raw materials and on tyre imports to augment local production in the first two years, while ramping up capacity. Nigerian government’s more critical understanding of the implications of the ECOWAS/EU Partnership Agreement also signifies a new level of enlightened self interest towards job creation opportunities for its teeming youth population, while ensuring value addition to its abundant major tyre manufacturing raw materials, such as natural rubber and carbon black, both of which make up about 70% volume. Both Nigeria's petrochemical and steel resources also hold strong promise to provide the bulk of the remaining major raw materials for tyre manufacturing, into the future.
Nigeria-based Stallion represents the premier tyre brand Apollo Tyres in Nigeria, marketing the product on a country-wide basis through its well entrenched network of outlets. Stallion leverages on its established strengths within the automobile industry as a market leader in West Africa for several years. Apollo Tyres South Africa [Pvt] Limited, is a wholly owned subsidiary of Apollo Tyres Limited in India located in South Africa, the core business is the manufacture and distribution of Dunlop tyres in South Africa and the thirty two countries in which Apollo Tyres Limited owns trade mark rights to the Dunlop brand. Apollo Tyres South Africa, with Dunlop as its premium brand, manufactures high quality tyres for every motoring application. Passenger tyres are manufactured in a high-tech production factory in Ladysmith, while truck tyres are manufactured in similarly technologically advanced Durban facilities. Apollo Tyres is committed to exceeding customer expectation and enhancing stakeholder value through a dedication to teamwork trustworthiness and ethical, safe practices. The group also manages an exclusive brand portfolio of automobiles including Honda, Hyundai, Porsche, Volkswagen, Audi, Skoda, Mahindra and Ashok Leyland.
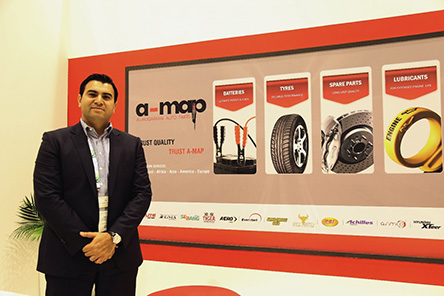
Asad Badami, Managing Director of Al Muqarram Auto Parts Al Muqarram Auto Parts (A-MAP) started its operations in South Africa in 2006 under the name AL MUQARRAM DISTRIBUTORS CC. Its office is located in Johannesburg, which is the business hub of the Southern African region. The major products distributed through our South African distribution facility are SOLITE batteries and ASIMCO auto parts. Driven by its on-going success Al-Muqarram Auto Spare Parts Trading (A-MAP), one of the largest distributors of automotive products in the region, is poised for further expansion. Located in the heart of Dubai’s main business trading hub, Deira, A-MAP presently operates a network of branches in Qatar, China, South Africa, Russia and USA. The company also exports a range of automobile spare parts to several African countries. Mr. Asad Badami, Managing Director, enthusiastically commented “Our growth is not a question of chance but is a result of various resources working together. We believe there is no limit to growth because there is no limit to hard work, imagination and evolving strategies. Today’s markets are seamless and we as a team are determined to penetrate new territories and demonstrate the A-MAP advantage.” Having recently launched a new development project in Jebel Ali Free Zone, A-MAP’s new warehouse and office facilities are currently under construction and should be completed by early 2017. Further to expanding its facilities, A-MAP has also recently opened its own distribution facilities in the Qatar and Russian markets. In a constant search for expansion, A-MAP’s product team continue their plan to launch new brands in the aftermarket. Achilles tyres has been added to the company’s portfolio when an agreement with an Indonesian firm was signed for the distribution of their product. The recent agreement with Sharjah Municipality to supply Solite automotive batteries for their fleet is also a significant milestone for A-MAP, adding to the list of reputed companies, departments and institutions to its fleet portfolio. The agreement also reinforces the company’s excellence and capabilities to offer 360-degree service in line with partners’ requirements and specifications.
Preliminary request for participation in the trade show
place
calendar_today
Preliminary request for visitor registration
Visitor Registration
place
calendar_today